Health insurance for families
Appropriately insured at every stage.
From the first preventive appointment to braces: With every year of your child’s life, the requirements for health insurance change too. We show you what basic insurance covers – and where supplementary insurance is worth a closer look.
(AXA Switching Report 2025)
Background
Why this topic is important

Basic insurance covers the essentials – not everything
Doctor visits, hospital care, medication, emergencies, maternity and vaccinations are mandatory benefits. Braces and gym memberships are not.

Children grow quickly
Every stage brings new health topics that parents are not always prepared for.

Those who compare early have more choices
Supplementary insurance policies require a health check – the earlier, the simpler.

Families save measurably
Independent comparison saves an average of CHF 456/year per person, up to CHF 3,480/year per family.
In short, explained
Basic insurance vs. supplementary insurance
The most important questions answered directly and briefly.What is the difference between basic health insurance and supplementary health insurance?
Basic insurance (OKP, KVG) is mandatory – every insurer must accept you and all offer identical benefits; the difference is the price. Supplementary insurance (VVG) is voluntary and the insurer may require a health assessment.
Does my child need supplementary insurance?
Not necessarily – but many everyday family benefits such as braces, glasses, swimming courses, complementary medicine and emergencies abroad are not covered, or only partly covered, by basic insurance.
What is not covered by basic health insurance for children?
Dental treatment (except after an accident or for a serious illness), gym memberships and massages, many forms of complementary medicine not performed by a doctor, and comfort benefits such as a private room.
Is it worthwhile to take out supplementary insurance early?
Yes – supplementary insurance requires a health assessment. Children without pre-existing conditions have the best chance of being accepted without exclusions, often without a medical certificate.
Does Switzerland have family insurance?
No. Every family member takes out their own health insurance. Some insurers do, however, offer family discounts.
Benefits by age
Toddlers to teenagers
Click on a life stage to see where supplementary insurance makes a difference.
Well supported from the beginning
Preventive examinations covered
Safe through childhood
Vaccination costs? Covered.
Gently find peace
Natural help for sleep problems
Just dive in!
We contribute – for every course
This is how Switzerland is organized
Basic and supplementary insurance
Mandatory – Basic Health Insurance (KVG)
- Every health insurance company must accept you – regardless of age or health.
- All health insurance funds offer identical services; the only difference is the price.
- Covers doctor visits, general hospital stays, medications, emergencies, maternity and vaccinations.
- No cashback possible – but comparison saves an average of CHF 456 per year.
Voluntary supplementary insurance (VVG)
- You decide what else is insured.
- Health check possible, with reservations regarding pre-existing conditions.
- Covers semi-private/private, dental, eyeglasses, complementary medicine, international travel and much more.
- Cashback up to CHF 300 per person when booking through alletta.
Change basic insurance
- Annually, cancellation by November 30 for January 1.
- Standard model with CHF 300 deductible: partly also available from July 1.
- Extraordinary cancellation in the event of premium increases.
Change supplementary insurance
- Usually annually, with a 3-month notice period.
- Exception: multi-year contracts.
- Only cancel your old policy once you have received confirmation from your new health insurance provider.
Waiting periods (maternity)
- None in case of accidents.
- In the case of maternity, usually 9–12 months.
- Sometimes 12 months for dentures.
Cost sharing
Franchise & Deductible
Focus on children – this applies equally to every health insurance fund.Adults (26 and over)
- Franchise CHF 300–2,500
- Deductible 10%, max. CHF 700/year
- Hospital fee CHF 15/day
Young adults (19–25)
- Same levels as adults
Children (0–18)
- Franchise CHF 0–600
- Maximum deductible: CHF 350/year
- No hospital cost contribution
Supplementary insurance in detail
Additional protection with supplementary insurance
Grouped by topic – the short version is always visible and the details can be expanded.Everything about preventive check-ups and the birth of your child.

Preventive check-ups & vaccinations
CoveredBasic vaccinations (GV)
CHF 500–1,500Additional insurance / year
Basic insurance
Pediatric preventive check-ups and vaccinations under the Swiss vaccination plan are covered.
Supplementary insurance
Adds further preventive-care years and vaccinations outside the standard program – usually 80%, CHF 500–1,500/year.

Maternity & Birth
CHF 0.–Franchise (GV)
Free choiceHospital / Midwife (ZV)
Basic insurance
Pregnancy check-ups, birth, midwifery services and breastfeeding advice are covered without a franchise.
Supplementary insurance
Enables a family room, free choice of midwife and hospital, and additional preventive care.
This is how you save the most money
Practical tips for your consultation
Here are a few simple rules of thumb to help you make the right choice when using the alletta app for advice.
Basic insurance
Model: Choose the appropriate model (family doctor, Telmed, HMO) – this is where you can save the most on premiums.
Accident: If you work at least 8 hours per week, you are already covered by your employer’s accident insurance – in this case, health insurance without accident coverage is sufficient. If you work less, choose insurance with accident coverage. Always include accident coverage for children.
Franchise: If your annual healthcare costs are below CHF 2,000, choose the CHF 2,500 franchise. If they are above that, choose CHF 300. Always choose CHF 0 for children.

Additional insurance
Outpatient supplementary insurance: During the consultation, use the alletta app to specifically look at the topics that are important to you – e.g. fitness, glasses or orthodontics.
Supplementary hospital insurance: It depends on your needs and budget. Often affordable and effective: general hospital coverage with free choice of hospital – giving you free choice of hospital throughout Switzerland.
Dental insurance: Take out at least minimal coverage – and submit dental hygiene invoices, for example, as proof.

Basic and supplementary insurance from different providers
If you do not want to take out basic and supplementary insurance with the same health insurance company, simply go through the consultation process twice: once for basic insurance and once for supplementary insurance.
In just a few steps
This is how the check with policy comparison works at alletta
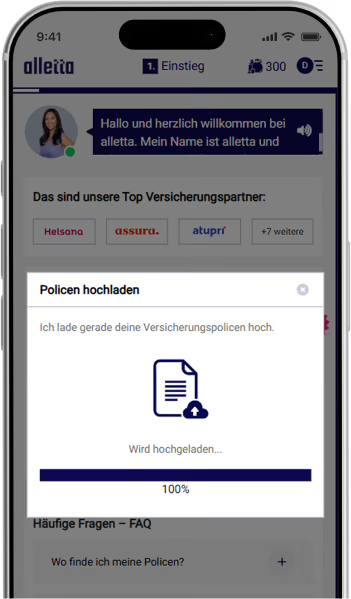
Upload policy report
Have your existing policy read in via SmartReader
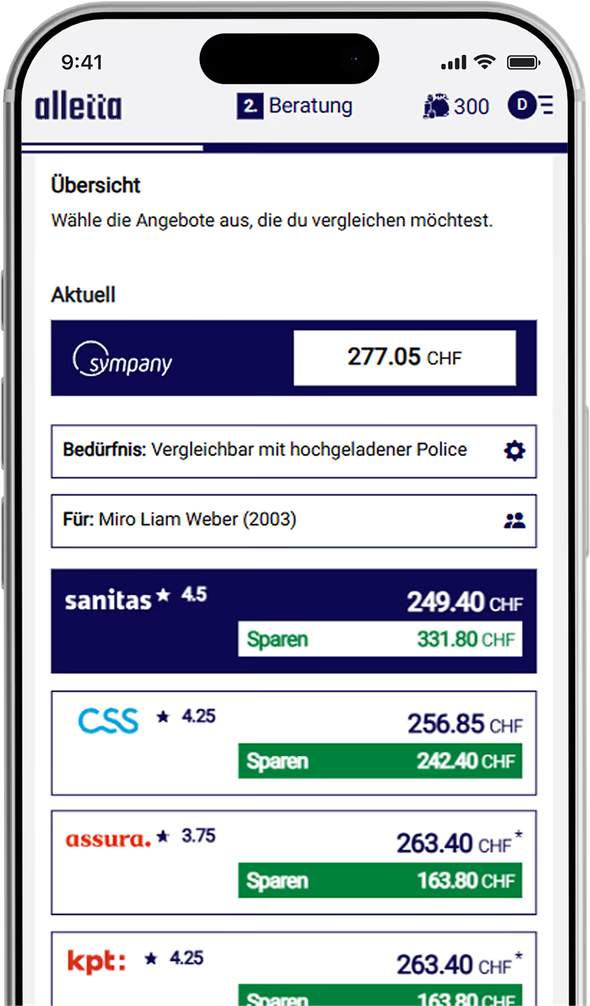
Compare offers
Basic and supplementary insurance transparently side by side
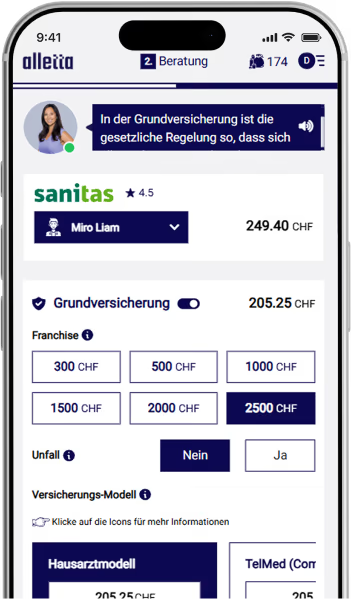
Choose the right option and save
Select the best offer for the whole family
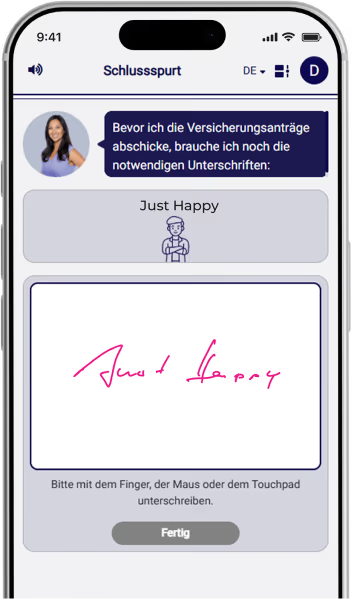
Complete digitally
Sign – in under 10 minutes, completely paperless
Your benefits
Only alletta offers this.

Accompaniment by the avatar
Guides you step by step through the consultation and answers your questions directly.

Advise yourself in your language
The self-guided consultation is available in 10 languages.

Independent comparison
Transparent and easy to understand – no pressure from advisers.

Completion 100% online
No paperwork, no appointments, no back and forth.

Cancellation service included
When you switch, alletta also helps with the cancellation.

Cashback upon completion
Up to CHF 300 per person with supplementary insurance; basic insurance saves an average of CHF 456/year.
FINMA registered: F01442247
Data secure: Servers in Germany, GDPR compliant
Transparently financed – cashback instead of hidden commissions
Before a coverage gap turns into a problem.
Digital, transparent, for the whole family – checked in under 10 minutes.
Start insurance check
Still questions?
Frequently Asked Questions
How does the health assessment work for children?
When supplementary insurance is taken out, the insurer asks about the child’s health. Healthy children are usually accepted without complications, often without a medical certificate.
Are there waiting periods for dental-care insurance?
Yes. General treatment often has a waiting period of 3–6 months. The waiting period usually does not apply after an accident.
Can I change my supplementary insurance at any time?
It can generally be cancelled annually, usually 3 months before the end of the contract – except for multi-year contracts. Only cancel the old policy once the new insurer has accepted you.
When does supplemental dental insurance become worthwhile?
Early – often before the 5th birthday without any certificate, before orthodontic issues arise at all.
How exactly does the cashback work?
You complete the policy digitally through alletta, the insurer pays alletta a commission, and part of it is credited to you as cashback – by bank transfer or donation.
Can I change my basic health insurance at any time?
Through an ordinary cancellation by 30 November for the following 1 January.