Health insurance premiums 2027

The average premium rises to 412 francs per month.

Across Switzerland, insured people will pay on average 5 percent more for basic insurance in 2027. Depending on the canton of residence, the increase is between 3.0 and 6.6 percent.
Compare premiums now
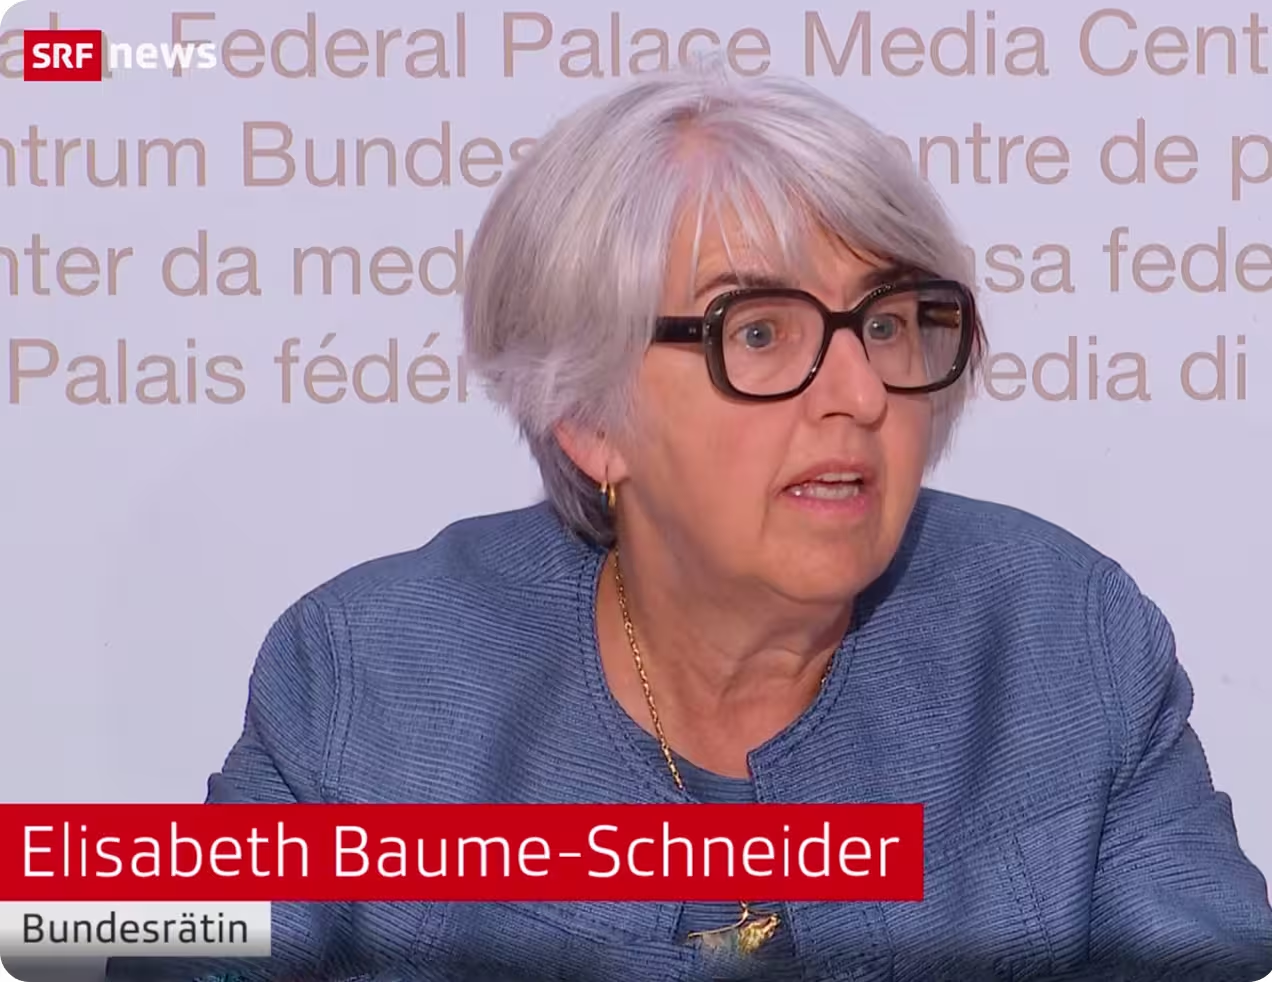
Federal Councillor Elisabeth Baume-Schneider at the media conference on the 2027 health insurance premiums

Federal Councillor Elisabeth Baume-Schneider at the media conference of 29.09.2026. Image: SRF News

Increase in average premium

+5.0 %
compared with last year

per month

+19.70CHF
francs more

per year

4’944CHF
average premium

Data: FOPH, premium approval 2027 · Annual premium calculated (12 × CHF 412) · Presentation: alletta

All age groups are affected similarly

The increase differs by only a few tenths of a percent between children, young adults and adults. Average monthly premium, Switzerland.

Adultsaged 26 and over
487.60CHF
+4.9 %+ CHF 22.80 per month
Young adultsaged 19–25
338.80CHF
+4.8 %+ CHF 15.40 per month
Childrenaged 0–18
128.10CHF
+4.6 %+ CHF 5.70 per month

Data: FDHA/FOPH, press release of 29.09.2026 · Presentation: alletta

Cantons
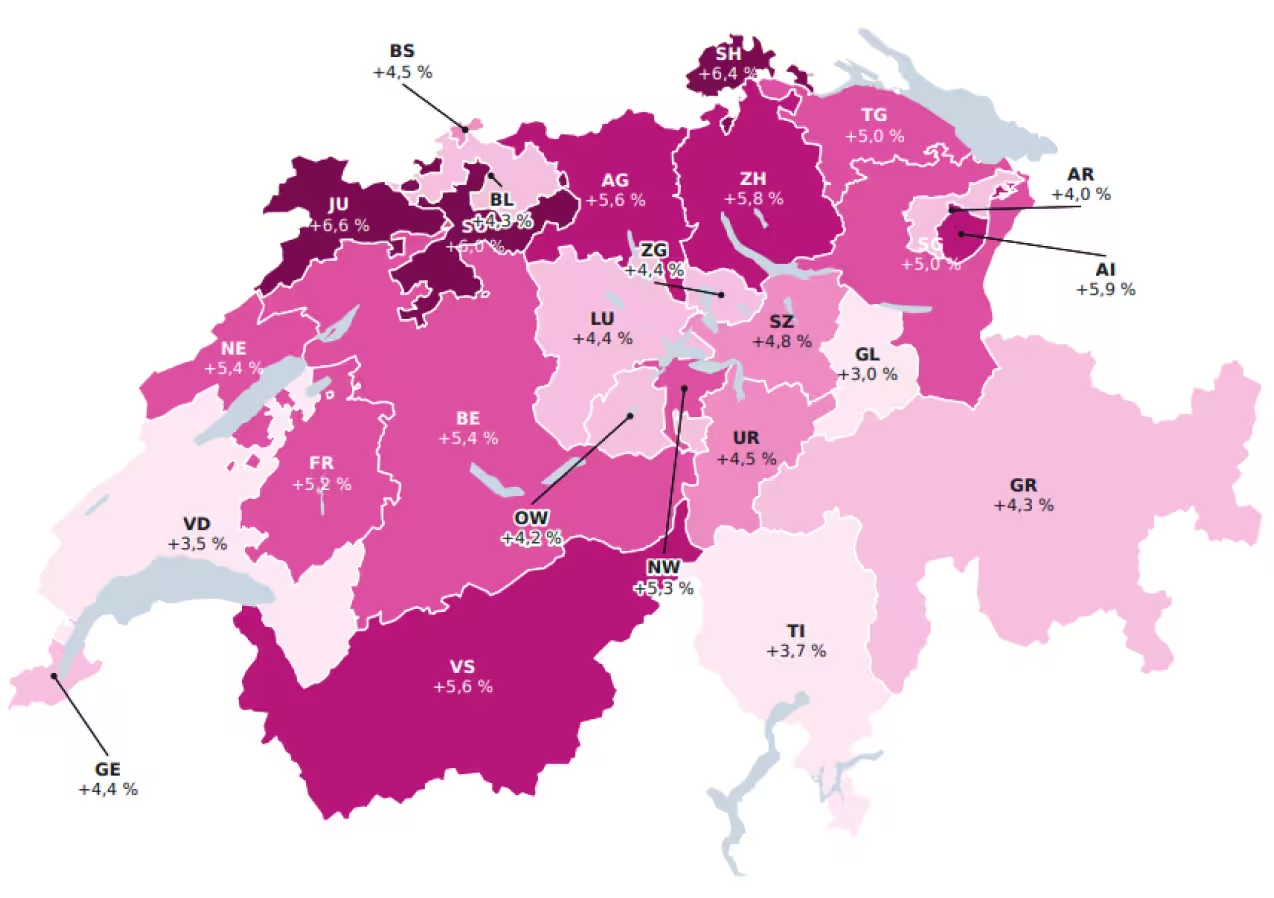
Jura and Schaffhausen at the top

The biggest increase is in Jura at 6.6 percent. In Zurich, the most populous canton, it is 5.8 percent or 22 francs per month. Glarus gets off most lightly at 3.0 percent.Increase in the average premium
  • under 4.0 %
  • 4.0 – 4.4 %
  • 4.5 – 4.9 %
  • 5.0 – 5.4 %
  • 5.5 – 5.9 %
  • 6.0 % and above
Average monthly premium across all age groups, incl. optional deductibles and models. Data: FOPH, premium approval 2027 · Map and presentation: alletta.
Map of Switzerland showing the 2027 premium increase by canton
Background

Why costs keep rising

Premiums have to cover the expected costs of basic insurance. If costs rise, premiums rise. The Confederation currently sees no signs that growth is slowing.

+5.3 %
Cost growth in basic insurance 2025
+4.7 %
expected cost growth 2026 (FOPH projection)
10.07
CHF bn for outpatient doctor visits, the largest cost block
6.69
CHF bn for medication, in second place
01

More treatments per person

The main driver: each patient receives more services. According to the Federal Council, illnesses themselves have not become more frequent.
02

An ageing population

According to the Confederation, about a third of the cost increase is due to demographic ageing.
03

New, expensive medications and therapies

Basic insurance keeps taking on new treatments. High-priced preparations such as weight-loss injections (GLP-1) are a significant factor.
04

Care by family members and psychotherapy

Family carers can now bill their services through health insurance. These costs have grown as strongly as those of psychotherapy.
05

Uncertainty from the new doctors’ tariff

The Tardoc tariff has applied since the start of 2026. Many invoices arrive late; the FOPH expects it to become more expensive than planned. First corrections apply from 2027.
06

Catching up from 2026

The 2026 premiums probably did not fully cover costs. The 2027 premiums therefore also have to close part of that gap.

What basic insurance pays for

In 2024, basic insurance reimbursed medical services worth CHF 42.2 billion, on average CHF 391 per insured person per month (incl. deductible and co-payment).

Three quarters of this goes to doctors’ practices, medication and hospitals.

Data: FOPH, Priminfo “cost groups of compulsory health insurance (OKP)”, 2024 · “Other” calculated as the difference to the total, presentation: alletta. Shares rounded.
Cost groupTotal (CHF)per person (CHF)Share
Outpatient doctors
9.3 bn
86 /mo.
Medication
9.2 bn
85 /mo.
Inpatient hospital
7.8 bn
72 /mo.
Outpatient hospital
5.8 bn
54 /mo.
Nursing homes
2.2 bn
21 /mo.
Other (Spitex home care, physiotherapy, laboratory, psychotherapy etc.)
7.8 bn
73 /mo.
Total
42.2 bn
391 /mo.
Sources: FDHA/FOPH, press release on 2027 premiums of 29.09.2026 (cost growth 2025 and 2026, main driver); FOPH, Priminfo “cost groups of compulsory health insurance (OKP)” (data 2024); statements at the media conference of 29.09.2026 and media reports of the same date (Watson, 20 Minuten, CH Media) on demography, medication, care by family members, psychotherapy, Tardoc and catching up. Cost blocks 2025 (doctor visits, medication) according to the Federal Council via 20 Minuten. Presentation: alletta.
Guide · 6 tips

6 tips: how to save on health insurance in 2027

The benefits of basic insurance are the same by law at all health insurers. What you pay depends on insurer, deductible and model.

01

Switch health insurer

In several cantons, the cheapest and the most expensive insurer differ by more than 100 francs per month for identical benefits. Your cancellation of basic insurance must reach your insurer by 30 November; preferably by registered mail.
Learn more: switching & deadlinesHow to cancel properly
Compare 2027 premiumsAll insurers and models for your region
To the premium comparison
02

Choose a higher deductible

If you rarely see a doctor, a higher deductible (up to CHF 2,500) means significantly lower premiums. You should, however, be able to afford the amount in an emergency.
Learn more: deductible & cost sharing
03

Alternative model

GP, HMO, telemedicine or pharmacy models are cheaper than free choice of doctor. In return, you first go to the agreed point of contact.
Learn more: basic insurance models
04

Drop accident cover

If you work at least 8 hours a week for the same employer, you are insured against accidents there and can exclude the cover from your health insurance.
Learn more: accident insurance
05

Check premium reduction

If your income is low, the canton pays part of the premium. Entitlement and registration deadlines are set by each canton.
Responsible offices per canton
06

Check supplementary insurance too

Compare policy
Think of 2028 today: You can take out a new supplementary insurance now, starting 1.1.2028. The health check takes place when you apply – this secures your acceptance while you are healthy. Once done, the matter is off the table.
!Important
Important: for supplementary insurance, the cancellation deadlines of your contract apply, not 30 November. And a new insurer may reject you. So only cancel once the new policy is confirmed.
Learn more: supplementary insurance

Supplementary insurance is voluntary and often the bigger lever for savings. Check which benefits you really need and whether coverage overlaps. Basic and supplementary insurance do not have to be with the same insurer.

Sources: FOPH/Priminfo (deadlines for basic insurance, premium reduction); alletta (deadlines and notes on supplementary insurance). Compiled by alletta, as of September 2026.

Switch and save by 30 November

Basic insurance is the same at all insurers, only the premium differs. Compare the offers for your premium region.

Premiums in my canton